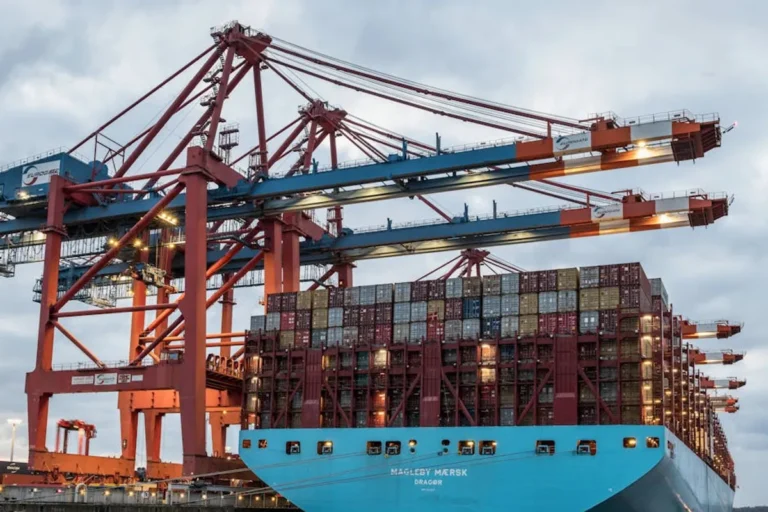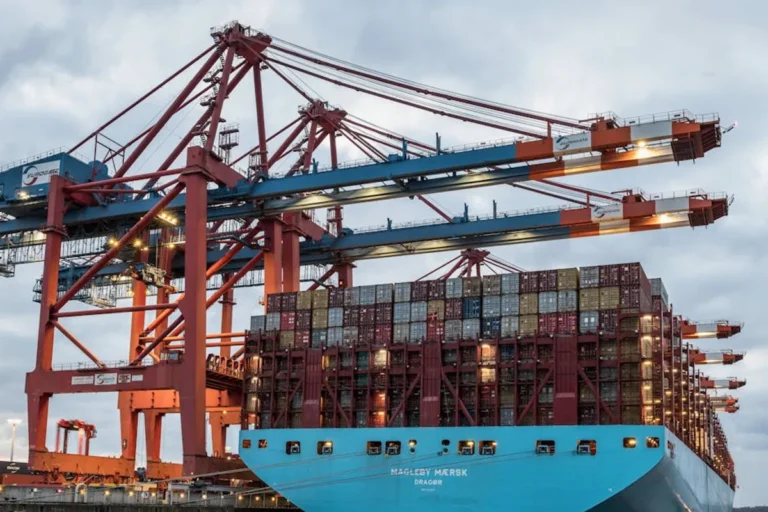
Importers navigating global supply chains face inherent risks that can quickly erode profit margins or halt operations entirely. Theft, damage, loss, or delays during transit are not anomalies but persistent threats. Relying solely on carrier liability, which is often limited by international conventions like the Hague-Visby Rules or the Montreal Convention, leaves significant financial exposure. A comprehensive maritime insurance policy acts as a critical safeguard, transferring these risks and ensuring financial continuity. The decision to invest in robust coverage is not merely a cost; it is a strategic investment in supply chain resilience and asset protection. This checklist provides a structured approach to evaluating and securing the appropriate maritime insurance, moving beyond basic coverage to address specific vulnerabilities unique to your cargo and operations. Understanding the fundamental principles of how maritime insurance works can provide peace of mind during transit.
Identifying Inherent Risks in International Shipping
Before selecting any policy, importers must conduct a thorough risk assessment specific to their goods, routes, and modes of transport. This involves recognizing the diverse threats that can impact cargo from origin to destination. Common perils include physical damage from heavy weather, collision, or improper handling; total loss due to sinking, fire, or piracy; and general average declarations, where all parties in a maritime venture proportionately share losses incurred to save the vessel or cargo. Beyond physical risks, consider political instability in transit countries, port congestion leading to demurrage charges, or even cyber-attacks impacting logistics systems. Each of these scenarios carries a distinct financial implication, underscoring the necessity of tailored coverage.
Selecting Appropriate Maritime Coverage Options
Maritime insurance is not a monolithic product; it comprises several specialized forms designed to address distinct aspects of the shipping process. Understanding these types is fundamental to building an effective checklist.
- Cargo Insurance: This is the most direct form, protecting the goods themselves against physical loss or damage during transit. Policies vary widely, from "All-Risks" coverage, which covers all perils not specifically excluded, to "Named Perils" policies, which only cover risks explicitly listed (e.g., fire, collision, stranding).
- Hull and Machinery (H&M) Insurance: While primarily for vessel owners, importers using chartered vessels may encounter clauses related to H&M, indirectly affecting their liabilities or the vessel's ability to complete a voyage.
- Freight Insurance: This covers the cost of freight itself, particularly if the cargo is lost or damaged and freight charges are still payable. For importers, this often means ensuring that prepaid freight is recoverable if the goods never arrive.
- Protection and Indemnity (P&I) Insurance: P&I clubs provide liability coverage for third-party claims, such as environmental damage, personal injury, or damage to port facilities. While typically for shipowners, importers can be indirectly exposed through contractual agreements or specific cargo types.
The choice among these options, and their specific clauses, directly impacts an importer's financial exposure. For instance, "All-Risks" coverage offers broader protection for high-value or fragile goods, while "Named Perils" might suffice for robust, low-value commodities where specific risks are minimal.
Essential Elements for Your Importer's Insurance Checklist
A structured checklist ensures no critical aspect of coverage is overlooked. This section details the key considerations for any importer.
Assessing Cargo Value and Nature
Accurately declare the full commercial value of your goods, including freight, duties, and a reasonable percentage for anticipated profit. For specialized or high-value items, consider specific endorsements. For example, perishables require clauses for spoilage due to refrigeration failure, while bulk commodities might need coverage against contamination or shortage.
Defining Voyage Scope and Incoterms
Clearly define the journey's start and end points, including any intermediate transshipments or storage. Your Incoterms (International Commercial Terms) are crucial here, as they delineate the point at which risk transfers from seller to buyer. For instance, under CIF (Cost, Insurance and Freight), the seller arranges and pays for insurance to the port of destination, but the risk transfers to the buyer once goods are loaded on the vessel. Under Ex Works (EXW), the buyer is responsible for all costs and risks from the seller's premises.
Evaluating Coverage Extent (All-Risks vs. Named Perils)
Best for high-value/fragile goods: All-Risks coverage, subject to policy exclusions. This offers the broadest protection, covering unforeseen events.
Best for robust/low-value goods: Named Perils coverage, which is more cost-effective but requires careful review of included perils. Ensure the policy explicitly covers risks relevant to your cargo and route, such as fire, explosion, stranding, sinking, collision, or discharge at a port of distress.
Reviewing Deductibles and Exclusions
Understand the deductible (excess) amount you must pay before the insurer covers a loss. Higher deductibles reduce premiums but increase your out-of-pocket expense per claim. Scrutinize policy exclusions thoroughly. Common exclusions include war, strikes, riots, civil commotions (often requiring separate War & Strikes coverage), inherent vice (damage due to the nature of the goods themselves), nuclear risks, and loss due to delay. Ensure your policy's exclusions do not negate coverage for your primary risks.
Understanding Policy Limits and Sub-limits
Verify that the total policy limit is sufficient to cover the maximum potential loss for a single shipment. Be aware of any sub-limits that may apply to specific types of goods (e.g., electronics, artwork) or particular perils. A sub-limit for theft, for instance, might be significantly lower than the overall policy limit, leaving a gap if high-value items are stolen.
Verifying Insurer Reputation and Financial Stability
Choose an insurer with a strong financial rating and a proven track record in handling maritime claims. A financially stable insurer ensures they can meet their obligations, even for large losses. Research their claims processing efficiency and customer service reputation.
Documenting Requirements for Claims
Understand the exact documentation required to file a claim, including timelines for notification. Typically, this involves bills of lading, commercial invoices, packing lists, survey reports, and damage reports. Proactive preparation of these documents can significantly expedite the claims process.
Pro Tip: Never assume standard carrier liability is sufficient. Carrier liability limits are often minimal, typically calculated per package or unit weight, and rarely cover the full commercial value of your goods. Always secure your own dedicated cargo insurance to bridge this significant financial gap.
Activating Coverage and Navigating the Claims Process
Once a policy is in place, activate it correctly for each shipment. This often involves providing shipment details to your insurer or broker before dispatch. In the event of a loss or damage, immediate action is crucial. Notify your insurer promptly and follow their specific instructions for surveys and documentation. Preserve all damaged goods and packaging, and collect evidence such as photographs, witness statements, and port authority reports. Timely and accurate submission of all required documents is paramount for a successful claim.
Regular Policy Review and Adaptation
Maritime trade routes, geopolitical landscapes, and the nature of goods imported can change rapidly. Conduct an annual review of your maritime insurance policy to ensure it still aligns with your current business needs and risk profile. Assess changes in cargo types, shipping volumes, new trade partners, or evolving Incoterms. Adjust coverage limits, add endorsements for new risks, or explore alternative policies if your operations have significantly shifted. Proactive policy management prevents coverage gaps.
Protecting Your Supply Chain: A Structured Approach
A well-executed maritime insurance strategy is not a reactive measure but a cornerstone of robust supply chain management. By meticulously applying this checklist, importers can transform potential financial liabilities into manageable risks. This structured approach ensures that assets are protected, operational continuity is maintained, and the financial impact of unforeseen events is minimized, fostering long-term stability and growth in international trade.
Frequently Asked Questions
What is the difference between "All-Risks" and "Named Perils" maritime cargo insurance?
"All-Risks" coverage protects against all perils of loss or damage to cargo, except those specifically excluded in the policy, offering broad protection. "Named Perils" coverage, conversely, only covers losses caused by risks explicitly listed in the policy, such as fire, collision, or stranding, making it more restrictive.
How do Incoterms affect my maritime insurance needs as an importer?
Incoterms define the point at which risk and responsibility for goods transfer from seller to buyer. Your insurance needs depend on this transfer point; for example, under EXW (Ex Works), the importer is responsible for insurance from the seller's factory, while under CIF (Cost, Insurance and Freight), the seller arranges and pays for insurance to the port of destination, though risk may transfer earlier.
When should I purchase maritime insurance for my imports?
It is crucial to have maritime insurance in place before your goods commence their journey. Coverage should ideally activate from the moment goods leave the seller's premises or warehouse, extending through all stages of transit, including loading, ocean voyage, transshipment, and unloading, until they reach your final designated warehouse.
What are the most critical documents needed to file a maritime cargo insurance claim?
Key documents typically include the bill of lading, commercial invoice, packing list, certificate of insurance, survey report detailing the damage or loss, and any correspondence related to the incident. Timely submission of these accurate documents is essential for a smooth claims process.