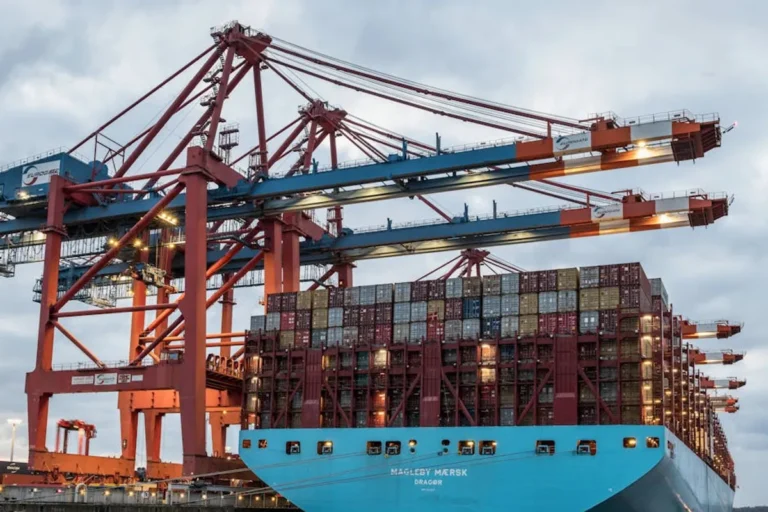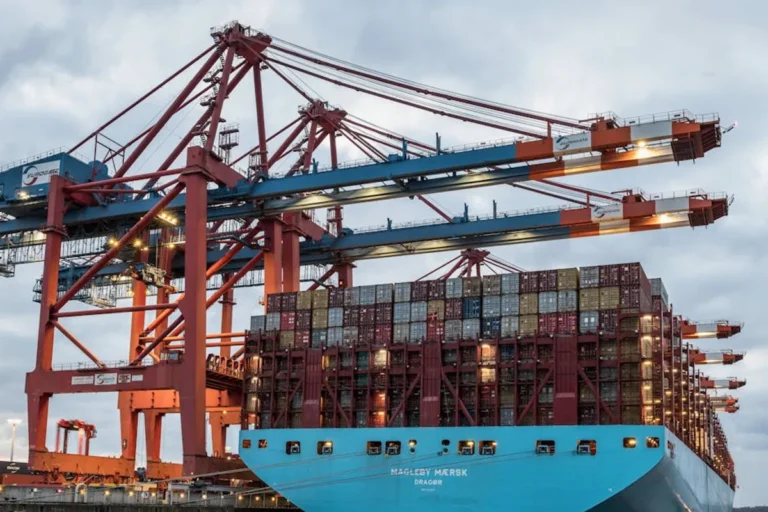
Maritime insurance serves as a fundamental pillar supporting the vast complexities of modern global trade. Without it, the inherent risks associated with transporting goods and vessels across oceans would render international commerce economically unfeasible for many. This specialized form of insurance mitigates financial exposure arising from perils at sea, ensuring continuity and stability for shippers, carriers, and all stakeholders in the supply chain. Understanding its mechanisms is not merely an exercise in risk management; it is a prerequisite for participating effectively in the global economy, directly impacting operational costs, liability frameworks, and strategic planning for logistics and trade professionals.
Defining Maritime Insurance in Commercial Context
Maritime insurance is a contract where an insurer agrees to indemnify an insured party against losses or damages specified in the policy, occurring during marine ventures. This extends beyond simple cargo loss, encompassing damage to the vessel, third-party liabilities, and other financial exposures integral to sea-borne trade. Its commercial utility lies in transforming unpredictable, high-impact risks into predictable, manageable costs (premiums), thereby enabling companies to budget for potential losses and maintain solvency even after significant incidents. Policies are typically governed by established international conventions and national laws, offering a standardized framework for risk allocation.
Core Categories of Maritime Coverage
The maritime insurance landscape is segmented into several distinct types, each addressing specific facets of risk associated with sea transport. Commercial entities must understand these distinctions to secure comprehensive protection tailored to their operational needs.
Hull and Machinery (H&M) Insurance
H&M insurance covers physical damage to the vessel itself, including its hull, engines, and equipment. This policy is critical for shipowners and operators, protecting their significant capital investment against perils such as collision, grounding, heavy weather damage, fire, and piracy. Coverage typically extends to repairs or replacement costs, salvaging expenses, and general average contributions. The value of the vessel, its age, trading routes, and safety record are primary factors influencing H&M premiums. Without H&M, a vessel owner faces the full financial burden of repair or total loss, a prohibitive risk for most shipping companies.
Cargo Insurance
Cargo insurance protects the goods being transported. This is essential for shippers, consignees, and freight forwarders, as it covers loss or damage to cargo from the point of origin to the final destination. Policies can be tailored to specific voyages or issued as open policies covering multiple shipments over time. Coverage types range from "All Risks" (subject to exclusions) to named perils, addressing risks like theft, fire, rough handling, and contamination. The commercial importance of cargo insurance is evident in preventing financial ruin for businesses whose profits depend on the safe arrival of goods, especially for high-value or time-sensitive commodities.
Protection and Indemnity (P&I) Insurance
P&I insurance covers third-party liabilities not typically included in H&M policies. This is mutual insurance provided by P&I Clubs, which are non-profit associations of shipowners. P&I covers a broad spectrum of risks, including:
- Loss of life, personal injury, and illness to crew, passengers, and third parties.
- Cargo liability (damage or loss to cargo not covered by cargo insurance due to carrier's negligence).
- Pollution risks (oil spills, environmental damage).
- Wreck removal expenses.
- Collision liability to other vessels (the portion not covered by H&M).
- Fines and penalties.
P&I is indispensable for shipowners, as it addresses the potentially catastrophic liabilities arising from maritime incidents that extend beyond damage to their own vessel or cargo. It ensures that shipowners can meet their legal and contractual obligations to third parties.
Freight, Demurrage, and Defence (FD&D) Insurance
FD&D insurance provides legal cost coverage for disputes relating to freight, demurrage, and other contractual issues arising from the operation of ships. It's a supplementary cover often provided by P&I Clubs, assisting shipowners with legal expenses incurred in pursuing or defending claims concerning charter party disputes, bill of lading issues, and other contractual disagreements. This coverage is crucial for managing the legal complexities and associated costs inherent in international shipping contracts.
Underwriting and Risk Assessment in Policy Formulation
Underwriting maritime insurance involves a detailed assessment of various risk factors to determine coverage terms and premiums. Insurers evaluate the type of vessel, its age, flag, management, and maintenance record. For cargo, considerations include the nature of the goods, packaging, shipping route, transshipment points, and geopolitical stability of origin and destination ports. The experience and claims history of the insured party also play a significant role. This rigorous assessment ensures that premiums accurately reflect the potential for loss and that policies are structured to address specific, identified risks, providing a financially sound basis for both insurer and insured.
Pro Tip: Always disclose all material facts accurately when applying for maritime insurance. Non-disclosure or misrepresentation, even if unintentional, can lead to a policy being voided or claims being denied, leaving your commercial operation exposed to substantial uninsured losses.
Impact on Modern Global Supply Chains
Maritime insurance is not static; it continually adapts to evolving global trade dynamics. Factors such as increased vessel size, geopolitical tensions (e.g., Red Sea transits), climate change impacts (e.g., extreme weather events, Arctic routes), and cyber risks necessitate constant adjustments in coverage and pricing. The rise of complex intermodal logistics means policies often need to cover "door-to-door" rather than just "port-to-port." For global supply chains, robust maritime insurance ensures resilience by providing financial recovery mechanisms, allowing businesses to absorb shocks and maintain operational continuity despite disruptions, whether from natural disasters, accidents, or human error. It facilitates trade by providing the necessary financial security for lenders, investors, and trading partners.
Securing Your Global Shipments
For any entity engaged in international trade, a proactive approach to maritime insurance is essential. Begin by conducting a thorough risk assessment of your specific operations, identifying potential exposures for vessels, cargo, and liabilities. Engage with specialized marine insurance brokers who possess deep expertise in the sector; their knowledge of market offerings and ability to negotiate terms are invaluable. Clearly define the scope of coverage required, paying close attention to exclusions, deductibles, and the conditions of average. Regularly review your policies to ensure they remain aligned with your evolving business needs and the dynamic nature of global commerce. Adequate insurance is not an optional expense but a strategic investment in the stability and longevity of your international trading activities.
Frequently Asked Questions
Is maritime insurance mandatory for all shipments?
While not universally mandated by law for all cargo shipments, it is often a contractual requirement in international trade agreements (e.g., Incoterms) and by lenders or financiers involved in the transaction. Vessel owners are legally required to carry P&I insurance under international conventions.
What factors influence maritime insurance premiums?
Premiums are influenced by the type and value of goods or vessel, the shipping route (including war risk zones or piracy areas), the vessel's age and condition, the insured's claims history, packaging quality, and the specific perils covered by the policy.
What is "General Average" in maritime insurance?
General Average is a principle where all parties involved in a sea venture (shipowner, cargo owners) proportionally share the losses resulting from a voluntary sacrifice of part of the ship or cargo, or expenditure incurred, to save the remainder of the property from an imminent common peril. Cargo owners must provide a General Average bond or guarantee for their cargo to be released.
Can maritime insurance cover cyber risks?
Traditional maritime insurance policies typically have exclusions for cyber-related losses. However, specialized cyber insurance policies or endorsements to marine policies are becoming more common to cover risks such as data breaches, ransomware attacks affecting vessel operations, or disruption to port systems.