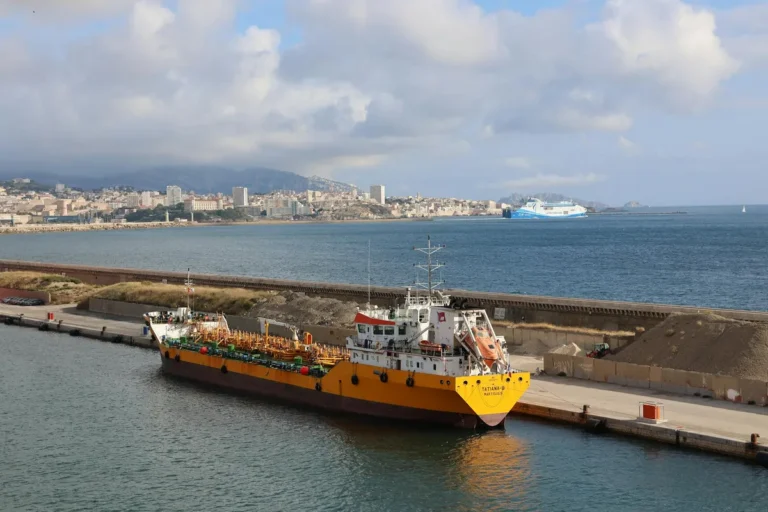
The IMO's 2023 revision to the greenhouse gas strategy set carbon-intensity targets that the maritime industry has been working through compliance planning for ever since. The container segment gets the bulk of the coverage on the regulation because the major container lines are the most visible and the most active on the alternative-fuels and energy-efficiency commitments. The tanker segment gets considerably less attention, and the operational reality for tanker operators is in some respects more demanding than the container coverage would suggest.
This piece works through what the IMO targets actually require, why the tanker segment is in a more constrained position than the container segment on several of the relevant compliance pathways, and what the contemporary view from the tanker operators and their advisers actually is. The aim is the kind of regulatory reporting that distinguishes what is mandatory from what is aspirational and that engages with the operational realities that the regulation is producing.
What the IMO targets actually require
The revised IMO strategy sets indicative checkpoints for 2030 of at least twenty percent and striving for thirty percent reduction in total annual greenhouse gas emissions from international shipping compared with 2008 baseline, and for 2040 of at least seventy percent and striving for eighty percent reduction on the same baseline. The full decarbonization target is by or around 2050, with national flexibility on how member states implement.
The implementation mechanism that matters most operationally for individual ships is the Carbon Intensity Indicator framework, the energy efficiency requirements for new builds, and the developing market-based measures that are working through the IMO process. The CII framework rates ships on annual operational efficiency, and the rating thresholds tighten progressively through 2026 and into 2030 in ways that operators have been working through compliance planning for.
The market-based measure that is most active in the IMO discussions is some form of greenhouse gas pricing, with the mid-term measures package targeted for adoption in 2025 and entry into force in 2027. The structure of the measure is still under negotiation, but the trade-press consensus is that some form of levy or trading mechanism will likely be adopted on a timeline that has the tanker segment among the more exposed.
Why the tanker segment is more constrained than container
The tanker segment's structural position on the IMO compliance pathways differs from the container segment in several substantive ways that the general coverage of maritime decarbonization rarely engages with.
First, the operational profile of tankers makes some of the energy-efficiency interventions less effective than they are for container vessels. The voyage patterns, the loaded-versus-ballast leg dynamics, and the cargo handling requirements all interact with the efficiency measures in ways that constrain the achievable intensity improvements without fundamental fuel changes.
Second, the tanker segment has been less active on alternative-fuel commitments than the container segment, principally because the customer base for tanker services has been less willing to support the cost premiums that alternative fuels currently command. The container lines have customer commitments for low-carbon ocean transport from major shippers willing to pay green premiums. The tanker market does not have an equivalent customer-side demand structure for low-carbon transport, and the operators have been correspondingly more cautious about ordering vessels designed for alternative fuels.
Third, the cargo itself in the tanker trades is principally hydrocarbon — crude oil, refined products, and to a lesser extent gas and chemicals. The cargo is in long-term decline as a share of global energy as the energy transition progresses, and the long-term fleet planning question for tanker operators is more complex than the question for container operators whose cargo base is structurally growing.
What the tanker desks are actually worried about
The conversations I have been having with tanker operators and their advisers through 2025 and into 2026 have a consistent set of themes that distinguish the tanker compliance picture from the container picture.
The CII rating thresholds for 2026 and 2027 are achievable for most modern tankers operating at typical voyage patterns. The thresholds for 2028 onwards are tighter and require either operational changes that reduce voyage flexibility or fuel-side changes that depend on alternative-fuel availability the market does not yet have. The operators are concerned about the operational flexibility implications of meeting the tighter thresholds without the fuel-side options being available at scale.
The market-based measure pricing the IMO is working toward is a particular concern for the tanker segment because the operators have less ability to pass the cost through to customers than the container lines do. The container BCO contracts have evolved structures for passing through bunker adjustments and have been adapted to handle additional carbon-related cost components. The tanker time-charter and voyage-charter structures have less developed mechanisms for the kind of cost pass-through that a carbon levy would require, and the renegotiation of the contracting framework is going to be substantial work.
The newbuilding question for tankers is also less clear than for container vessels. The major container lines have made commitments to alternative-fuel newbuilds — methanol, ammonia, and LNG-dual-fuel options at scale. The tanker orderbook is much more weighted toward conventional fuel vessels, and the operators face genuine uncertainty about which alternative-fuel pathway will mature on a timeline that supports newbuilding decisions in the next several years.
The trading-pattern adjustments that are already happening
Some of the operational adjustments tanker operators are making to position for the tightening regulation are already visible in the trading data. Speed reduction has been one of the principal adjustments, with average voyage speeds for the principal tanker segments down measurably from the levels that were typical in the late 2010s. Speed reduction reduces fuel consumption and CII rating exposure but also reduces effective fleet capacity and produces compensating effects on the tonnage demand picture.
Voyage routing decisions are increasingly being made with explicit attention to CII implications. The accumulation of slow-steaming, weather routing, and voyage optimization measures has produced measurable intensity improvements that have helped operators stay ahead of the tightening thresholds. The pace of further improvement from these operational levers is slowing as the easier gains have been captured.
The fleet renewal pace is also adjusting. Operators with older, less-efficient vessels are facing earlier scrapping decisions than they would have without the regulatory pressure, and the newbuilding decisions for replacements are being made with attention to the regulatory environment that will apply through the vessel's twenty-five to thirty year economic life. The investment economics of these decisions are not straightforward in the current environment of regulatory uncertainty and alternative-fuel uncertainty.
What the alternative-fuel pathways look like for tanker operators
The principal alternative-fuel pathways under serious commercial consideration for tankers are LNG, methanol, and ammonia, with biofuels as a supplementary option for retrofit on existing vessels. Each pathway has substantial uncertainty around supply availability, infrastructure development, and operational characteristics that affect the investment decision.
LNG-fuelled tankers have the most mature supply infrastructure and the longest operational track record, but the well-to-wake emissions profile is less favorable than the tank-to-wake numbers alone would suggest. The methane slip question and the upstream emissions accounting in the IMO's lifecycle methodology mean that LNG is a partial-solution rather than a full-solution pathway for the longer-term targets.
Methanol is the pathway that several major container lines have committed to at scale. The tanker segment has been more cautious, partly because the customer-demand structure has not supported the cost premium and partly because the supply of low-carbon methanol at scale is not yet developed. The operational characteristics of methanol on tankers are workable but require design choices that the orderbook is not yet weighted toward.
Ammonia is the pathway that several major fuel-cell and engine OEMs are developing aggressively. The first commercial ammonia-fuelled deep-sea vessels are at sea or in delivery, and the technical pathway is becoming more credible. The supply side and the safety-handling questions are the principal remaining concerns, and the tanker segment's prior experience with handling ammonia and other hazardous cargoes positions the segment well for ammonia adoption when the supply side develops.
What the segment-level outlook actually is
The tanker operators I talk to are not in panic mode about the regulation. The compliance pathways exist, the operational adjustments are working through, and the segment has handled major regulatory shifts before. What they are doing is working through the operational and contracting changes that the regulation requires in ways that take time and that produce real costs.
The segment-level investment outlook is more cautious than the container segment's. The newbuilding orders for tankers in 2025 came in below the levels the supply-demand fundamentals would have supported in a less regulation-uncertain environment, and the trend through early 2026 has continued. The implications for tanker tonnage supply later in the decade are that the fleet may be tighter than the demand picture would have suggested in an environment of clearer regulatory pathways.
The chartering market is reflecting some of this in period-rate firmness across several tanker segments. The structural picture for tanker rates over the next few years is supported by the slower fleet growth that the regulatory uncertainty is producing, alongside the demand-side factors that the energy transition is working through more gradually than some forecasts have suggested.
The regulation is working as intended in the sense that it is producing fleet-level adjustments that align with the decarbonization trajectory the IMO targets imply. Whether the pace is right and whether the segment-level effects are well-calibrated to the broader policy aims are separate questions that the next round of IMO negotiations and the implementation of the market-based measures will be working through. The tanker desks will be watching.